How Trip Cancellation Insurance Protects Families?
Table of Contents
Trip cancellation insurance acts as a vital financial shield, ensuring your family’s travel investments are protected if unforeseen circumstances force you to abandon your plans.
This protection is an integral part of how to plan a family vacation step by step, ensuring every aspect of your journey is secure from unpredictable events.
1. Why Should Families Consider Trip Cancellation Insurance for Travel?
Families must consider trip cancellation insurance because it guarantees reimbursement for significant, non-refundable expenses when a trip is derailed by emergencies. This protection is especially crucial for complex or expensive family trips where the financial stakes are high.
For a more comprehensive understanding of securing your vacation, explore how to plan travel insurance for a family vacation and make informed coverage decisions.
How does trip cancellation insurance safeguard family travel finances?
This insurance acts as a financial backstop, allowing your family to recoup money spent on non-refundable flights, accommodations, and tours. This reimbursement prevents the total loss of your vacation investment due to unforeseen circumstances.
With the average cost for a one-week domestic family vacation for four reaching approximately $4,500 in 2023, this protection covers a significant financial instrument, as highlighted by Experian.
Beyond major costs like flights and hotels, comprehensive policies can also cover smaller, often overlooked non-refundable expenses like pre-booked shore excursions, special event tickets, or private tour guide deposits, which add up significantly for a family.
What peace of mind does trip cancellation insurance offer parents?
The key peace of mind for parents is knowing that a sudden event, like a child’s illness, won’t result in a major financial loss. This removes a layer of stress from both the planning phase and the days leading up to departure.
According to a summer 2026 travel survey, 56% of Americans purchasing travel insurance are worried about trips getting cancelled or interrupted, a concern echoed in a Squaremouth survey.
The peace of mind is not just about a total cancellation. It’s also knowing you can make the “right” decision (e.g., staying home with a sick child) without the added pressure of losing thousands of dollars, which can lead to better family health and well-being choices.
Author’s Experience
“As a parent who’s meticulously planned family trips for years, I’ve seen firsthand how unpredictable life can be. Once, a sudden ear infection almost derailed our long-awaited beach vacation. Knowing we had trip cancellation insurance in place allowed us to prioritize our child’s health without financial worry, a true lifesaver.”
Why is family health a key concern without trip cancellation insurance?
Without insurance, a parent faces a difficult choice: travel with a sick child or lose the entire cost of the vacation. Trip cancellation coverage removes this financial penalty, making the health of a family member the top priority.
According to a 2023 analysis, medical issues are the number one reason for trip cancellations, accounting for nearly one-third of all claims, as reported by Generali Global Assistance.
This concern is heightened for families traveling with very young children, who are more susceptible to common illnesses (e.g., ear infections, fevers), or with elderly grandparents who may have more fragile health.
2. What Does Trip Cancellation Insurance Typically Cover for Family Travel?
A standard policy typically covers financial losses resulting from cancelling a trip due to a range of unforeseen events explicitly listed in the policy document. It is critical for families to understand that only these specified events trigger coverage.
What are the common covered reasons for family trip cancellation?
Standard policies cover a list of specific perils. Beyond health emergencies, this includes severe weather making a destination uninhabitable, a primary residence becoming uninhabitable (e.g., due to fire), jury duty, and involuntary job termination.
A “terrorist incident” is often a covered reason, but it has a very specific definition. It typically must occur within a certain number of days before departure and within a certain mileage of a city on the planned itinerary, a nuance families must understand.
Common Covered Reasons:
- Health-Related: Unforeseen illness, injury, or death of a traveler, close family member, or traveling companion.
- Weather/Disaster-Related: Severe weather making the destination uninhabitable; primary residence becoming uninhabitable due to fire, flood, or natural disaster.
- Personal/Work-Related: Jury duty; involuntary job termination.
Does trip cancellation insurance cover pre-existing conditions for family members?
Standard policies exclude losses from pre-existing conditions. However, families can get coverage for these conditions by purchasing a policy with a specific waiver, which has strict eligibility rules, such as buying the plan within a specific timeframe (e.g., 10-21 days) of the first trip payment.
Given that over 50% of U.S. adults have a chronic pre-existing condition, securing this waiver is not a luxury but a necessity for a vast number of traveling families, as revealed by an InsureMyTrip analysis.
The “look-back period” is the critical factor. The insurer will look back 60-180 days before the policy purchase date; if the condition was stable (no new treatments, medications, or symptoms) during that period, it may not be considered a pre-existing condition for the purposes of the new trip.
Beyond securing the waiver, proactive steps to ensure smooth travels are vital. Discover more about how to manage pre-existing conditions while on a family vacation for comprehensive preparation.
What specific family-related events are often included in policies?
Beyond standard covered reasons, some family-friendly policies include triggers specific to family life. These can include a requirement to attend a rescheduled school year event or, in some cases, the cancellation of a wedding.
A less common but valuable family-specific benefit is coverage if a school year is unexpectedly extended, forcing a conflict with the planned vacation dates. This is particularly relevant for families planning trips at the very beginning or end of summer break.
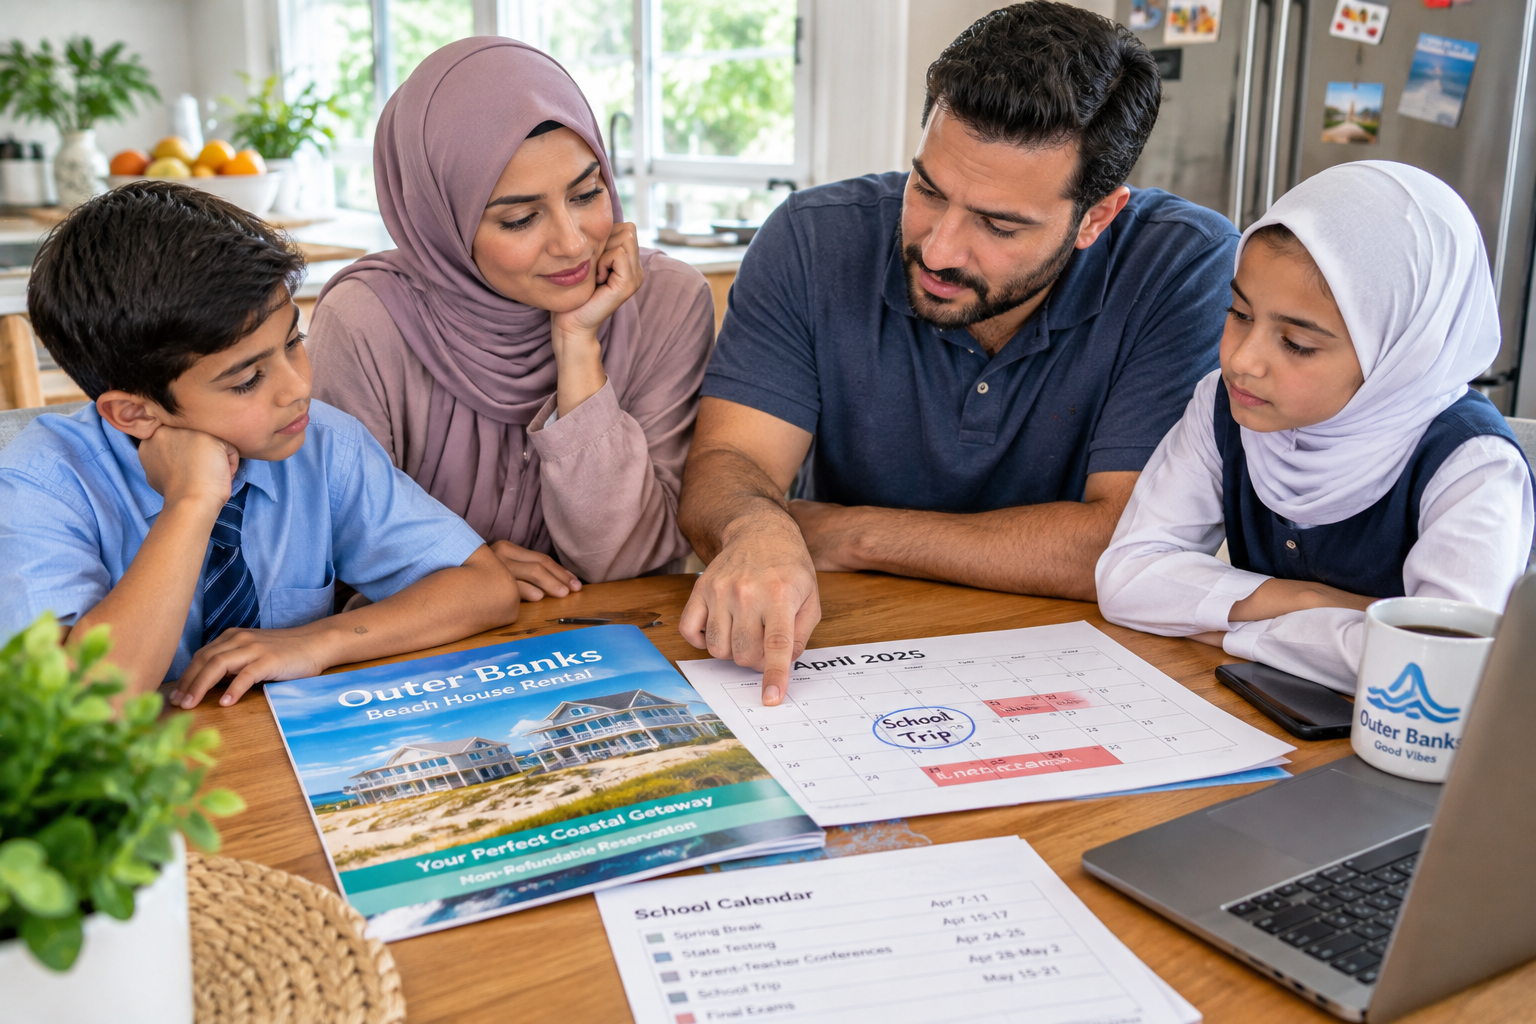
A snow day makeup week is added to the end of the school year, directly conflicting with your non-refundable beach house rental in the Outer Banks.
Knowing that school-related conflicts can unexpectedly arise, it’s also beneficial to consider how school schedules affect family vacation planning to mitigate potential disruptions.
3. How Can Families Choose the Right Trip Cancellation Insurance Policy?
The right policy is determined by finding a balance between cost and comprehensive coverage. Families must analyze the total value of their trip, the health of all travelers, and their own tolerance for risk to determine if a basic named-perils plan or a more flexible “Cancel for Any Reason” upgrade is most appropriate.
Which factors determine the best policy for your family’s travel needs?
To find the best policy, you must comprehensively evaluate your trip’s cost and your family’s specific vulnerabilities. A more expensive, complex trip with older or younger family members requires a more comprehensive and robust insurance plan than a simple domestic trip.
Comprehensive policies generally cost between 5% and 10% of the total non-refundable trip cost, providing a clear benchmark for budgeting.
The number of travelers is a key factor. A single policy covering a large family group (e.g., 10 people for a reunion) is often more cost-effective and easier to manage than multiple individual policies, but requires ensuring the policy limits are high enough to cover the entire group’s combined trip cost.
Factors for Policy Choice:
- Trip Cost: The total non-refundable investment made in flights, accommodations, tours, and other prepaid expenses.
- Traveler Ages/Health: The age range and current health status of all family members, including any pre-existing conditions.
- Destination & Time of Year: The chosen location and travel dates, considering potential weather risks or political instability.
- Risk Tolerance: The family’s comfort level with potential financial loss versus the cost of insurance.
How do “Cancel for Any Reason” (CFAR) policies benefit families?
CFAR provides the ultimate flexibility by allowing a family to cancel their trip for reasons not otherwise covered by a standard policy and still recoup a significant portion of their non-refundable trip costs. If a family needs to cancel for a reason not listed in their base policy (like a change of mind or a non-covered work conflict), CFAR allows them to recoup a significant portion, typically 75%.
A “Cancel For Any Reason” (CFAR) policy is flexible, allowing a family to cancel for any reason not on the covered list, but it typically only reimburses 50-75% of the trip cost.
CFAR is particularly valuable for families booking very far in advance (e.g., a year out) for a milestone trip, where personal circumstances, comfort levels with travel, or even relationship dynamics (e.g., a trip with extended family) can change in ways a standard policy doesn’t cover.
A family is concerned about a destination’s newly reported viral outbreak that isn’t yet a formal travel warning. CFAR allows them to cancel out of an abundance of caution and still recoup 75% of their investment.
What are the critical policy limits and deductibles for family plans?
Families must verify that the policy’s maximum trip cost limit is high enough to cover their entire non-refundable investment. Many family plans have a $0 deductible for trip cancellation, but it’s essential to check this in the policy details.
While many premium credit cards offer some travel insurance, their trip cancellation reimbursement is often capped at $10,000 per trip, whereas dedicated policies can cover total trip costs of $100,000 or more.
Policy limits are often expressed “per person” and “per policy.” For a family, the “per policy” limit is the most critical number to check, as a low per-policy limit might not be sufficient to cover the combined costs of all family members on an expensive trip.
4. When Should Families Purchase Trip Cancellation Insurance for Their Trips?
Buying insurance early is critical because it is the only way to become eligible for important time-sensitive benefits, most notably the Pre-existing Medical Condition Exclusion Waiver. Waiting to buy insurance limits coverage and increases risk.
What is the optimal window for buying family trip cancellation insurance?
The optimal window is a requirement set by insurers to qualify for key benefits like the Pre-existing Condition Waiver and CFAR coverage. Purchasing within this period maximizes the value and scope of the policy.
Purchasing within the early “purchase window,” typically 10-21 days, is required to be eligible for important supplemental benefits like pre-existing condition waivers and “Cancel For Any Reason” upgrades.
The “first payment” is the trigger. Even if it’s just a small deposit on a rental car, that action starts the clock on the 10-21 day window for the entire trip’s insurance eligibility for time-sensitive benefits.
How does early purchase enhance family coverage benefits?
Buying your policy within the specified time-sensitive period after your first trip payment is the only way to secure coverage for trip cancellations caused by a flare-up of a chronic condition. This is a critical enhancement for any family traveling with members who have ongoing health issues.
To be eligible for Cancel for Any Reason (CFAR) coverage, the policy must be purchased within 10-21 days of the initial trip payment.
Beyond the pre-existing condition waiver, early purchase also provides the longest period of protection. It protects the family’s investment against unforeseen events that could happen months before the trip, not just in the final days or weeks.
5. How Do Families File a Trip Cancellation Insurance Claim Effectively?
To ensure a smooth claims process, you must act quickly and be organized. Gather all relevant documents—such as cancellation invoices and a doctor’s note—before you begin, and submit a complete and accurate claim package as soon as possible.
What is the step-by-step process for a family claim?
The process is: 1) Notify all parties, 2) Obtain official documentation for the reason of cancellation (e.g., a doctor’s letter), 3) Gather all trip receipts and invoices, 4) Complete the insurer’s claim form accurately, and 5) Submit the entire package. Following these steps in order prevents delays.
According to one survey, 85% of Americans who purchase travel insurance say it is essential for their trips.
Many insurers now have online claim portals. Using the portal is often faster and allows for easier tracking of the claim’s status compared to mail or fax. Families should check for this option first.
Step-by-Step Claim Process:
- Notify All Parties: Immediately inform your travel suppliers (airline, hotel, cruise line) and your insurance provider about the cancellation.
- Document Reason: Obtain official documentation for the reason of cancellation (e.g., doctor’s letter, death certificate, police report).
- Collect Financial Records: Gather all trip receipts, booking confirmations, and invoices for non-refundable expenses.
- Complete Claim Form: Accurately fill out the insurance provider’s claim form, ensuring all sections are completed.
- Submit Package: Submit the complete claim package, including all documentation, to the insurer promptly.
What essential documents do families need for a trip cancellation claim?
You will need to provide proof of payment, proof of loss, and proof of the covered reason. This means collecting everything from initial booking confirmations to the final cancellation penalties issued by the airline or hotel, plus the doctor’s note or other official documentation explaining why you had to cancel.
A frequent mistake is assuming a simple “doctor’s note” is sufficient when most policies require a detailed “Physician’s Statement” form provided by the insurer.
For a medical cancellation, the doctor’s note must be specific. It should state the date of onset of the illness/injury, the diagnosis, and a clear recommendation that the family member is not medically fit to travel on the planned dates. A vague note will cause delays.
Essential Documents Checklist:
- Original trip itinerary and booking confirmations.
- Receipts and invoices for all non-refundable trip payments (flights, hotels, tours, etc.).
- Cancellation confirmations or invoices from travel suppliers, detailing any penalties or refunds received.
- Official documentation proving the reason for cancellation (e.g., doctor’s statement, death certificate, weather reports, employer’s letter for job loss).
- Proof of identity (e.g., copy of passport or driver’s license).
How can families ensure their claim for a canceled trip is approved?
Claim approval hinges on meeting the policy’s terms and conditions precisely. A claim is most likely to be approved when the reason is clearly covered, the documentation is irrefutable, and all deadlines for notification and submission are met.
Industry experts estimated in 2023 that more than half of all initially denied claims are not appealed, meaning policyholders may be leaving money on the table.
Be completely honest and accurate on the claim form. Any misrepresentation, even if seemingly minor, can be grounds for the insurer to deny the entire claim due to fraud. It is better to have a claim denied for a non-covered reason than for misrepresentation.
7. What Common Mistakes Should Families Avoid with Trip Cancellation Insurance?
Families often make mistakes like waiting too long to purchase a policy, not insuring the full non-refundable trip cost, or misunderstanding what a “pre-existing condition” is. Avoiding these pitfalls requires careful reading of the policy document before purchase.
How can families avoid coverage gaps in their insurance policies?
The best way to avoid gaps is to match the policy to your specific trip. If you need flexibility, a standard policy has a gap that only a CFAR upgrade can fill. If a grandparent has a heart condition, a policy without a pre-existing condition waiver has a massive coverage gap.
A “Cancel For Any Reason” (CFAR) upgrade typically increases a policy’s premium by 40% to 60% in exchange for this flexibility.
A common gap is related to adventure activities. Many standard policies exclude claims arising from activities like scuba diving, ziplining, or even skiing. Families planning such activities need to seek out policies with an “adventure sports” rider or coverage.
What are common reasons for denied family trip cancellation claims?
Claims are frequently denied due to three main issues: the event is not covered (e.g., canceling due to a work project), the claim is related to an uncovered pre-existing condition, or there is insufficient documentation to prove the loss.
The number one covered reason for Trip Cancellation and Trip Interruption is the unforeseen illness or injury of you or a traveling companion that deems you unfit to travel.
A claim can be denied if the family waits too long to notify the insurer of the cancellation. Policies have specific timeframes (e.g., “within 72 hours” or “as soon as reasonably possible”) for notification, and missing this deadline can void the claim, even if the reason was covered.
8. Logistics: Claim Filing Checklist for Family Trip Cancellation Insurance
| Checklist Item / Tactic | Status |
|---|---|
| STEP 1: Immediately notify travel suppliers & insurer of cancellation. | ⬜ |
| STEP 2: Obtain official documentation for cancellation reason. | ⬜ |
| STEP 3: Gather all trip receipts, booking confirmations, and invoices. | ⬜ |
| STEP 4: Accurately complete the insurer’s claim form. | ⬜ |
| STEP 5: Submit the complete claim package promptly. | ⬜ |
Resolution
Trip cancellation insurance acts as an essential tool for risk management, providing families with a financial safety net and the peace of mind to prioritize their health and well-being. By choosing the right policy, purchasing it early, and understanding the claims process, parents can effectively safeguard their family’s valuable vacation investment.