How to Plan Travel Insurance for a Family Vacation?
Table of Contents
Planning Travel Insurance: Protect your family vacation. Choose the right coverage, secure a financial safety net, and prevent major trip disruptions.
Specialized family travel insurance ensures multiple individuals are covered under one policy while addressing child-specific risks that standard policies may overlook. To guarantee your entire trip is financially sound, it’s wise to consider the broader aspects of How to Plan the Budget for a Family Vacation. Before diving into the specifics of insurance, understanding the comprehensive journey of How to Plan a Family Vacation Step by Step can provide invaluable context.
1. Why does a family vacation need specialized travel insurance?
A family vacation requires specialized travel insurance because the potential financial and logistical impact of unexpected events is exponentially higher when managing multiple people across different age groups. Specialized family travel insurance provides a financial safety net specifically designed for the unique vulnerabilities of a traveling family unit. This includes covering multiple individuals under one policy and addressing child-specific risks that standard policies may overlook.
What are the unique risks families face during travel?
The unique risks families face during travel stem from the unpredictability of children’s health, the complexity of coordinating multiple schedules, and the specialized equipment required for their care. Families face higher risks of trip disruptions due to child sickness, greater potential for lost or damaged essential items like car seats, and increased liability in public spaces. These risks require specific insurance considerations beyond a standard policy.
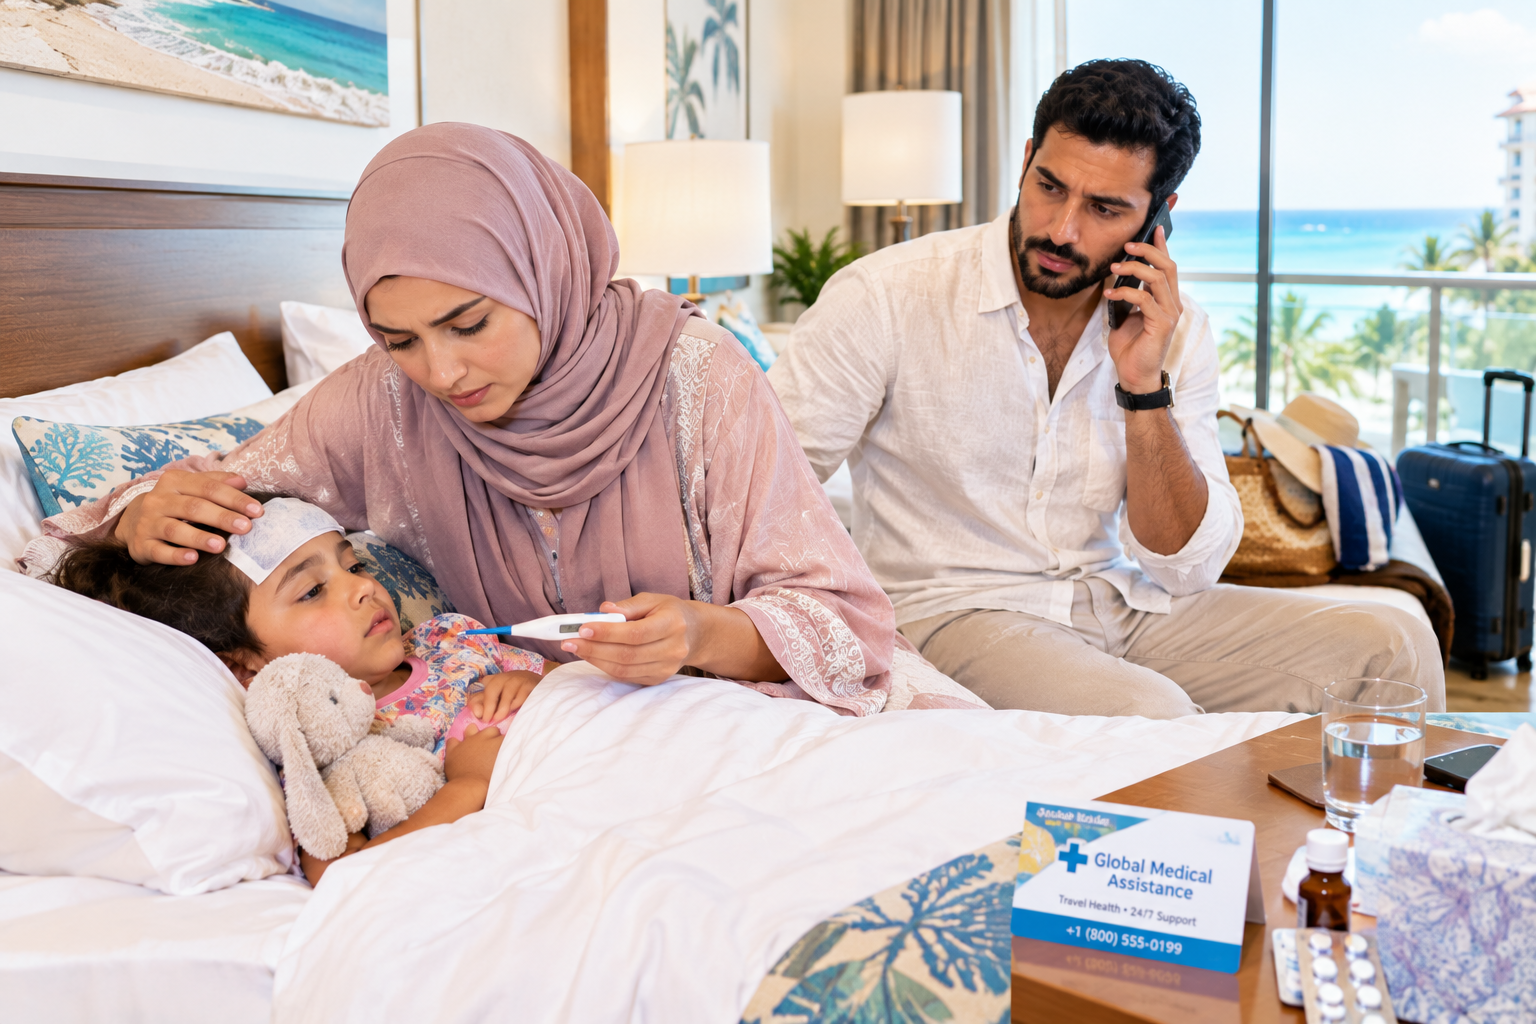
- Medical Risks: Child sickness, increased health consequences for children.
- Logistical Risks: Complexity of coordinating multiple schedules, greater potential for lost or damaged essential items (e.g., car seats, strollers).
- Financial Risks: Interdependency risk (one child’s illness affecting entire family’s plans), increased liability in public spaces.
According to the Centers for Disease Control and Prevention, while children may face the same health risks as adults while traveling, the health consequences can be more serious for children.
A critical but overlooked risk is “interdependency.” If one child gets sick and requires a parent to stay behind, a standard policy might not cover the costs for the other parent and siblings to continue or alter their trip. A family policy is designed to manage this interdependent risk.
Author’s Experience
“During a family trip to Japan, my youngest developed an unexpected fever the day before our flight. Having robust trip cancellation coverage meant we could delay without financial penalty, prioritizing his health over a rigid itinerary. It truly brought peace of mind.”
What is the primary purpose of family travel insurance?
The primary purpose of family travel insurance is to transfer the financial risk of unforeseen travel-related incidents from the family to an insurance provider. Its core purpose is to prevent a disruptive event, such as a medical emergency or cancelled flight, from becoming a catastrophic financial loss for the family. It ensures that the family’s financial stability is protected, allowing them to handle the emergency without facing crippling out-of-pocket costs.
Standard insurance covering emergency health care and cancellations typically costs about 5–10 percent of the total trip, according to Squaremouth.
The purpose extends beyond finance to “decision-making freedom.” In a crisis, having robust insurance removes cost from the equation, allowing parents to make the best decision for their child’s health and safety (e.g., choosing the best available hospital, not just the cheapest).
2. What types of travel insurance coverage apply to a family vacation?
The types of travel insurance coverage that apply to a family vacation are categorized into three main pillars: medical protection, trip and transit protection, and personal belongings protection. For a family vacation, essential coverage types include Emergency Medical and Dental, Medical Evacuation, Trip Cancellation/Interruption, Baggage Loss/Delay, and often specialized add-ons like ‘Cancel for Any Reason’ (CFAR). Each component addresses a specific category of risk inherent in family travel.
How does medical coverage protect a family during a vacation?
Medical coverage in a family travel insurance plan protects a family by paying for emergency medical and dental expenses incurred during a vacation, which are often not covered by domestic health insurance plans abroad. It functions by covering costs for hospital stays, doctor visits, ambulance services, and prescription medications for any covered family member who suffers an unexpected illness or injury. This protection is critical in countries with high healthcare costs, like the United States, or in remote destinations requiring evacuation.
Internal data from IMG Global shows that over 27% of all travel insurance claims are for a medical emergency, with an average payout of $1,816 per medical claim.
A key function is access to a 24/7 assistance provider. This service acts as a medical concierge, helping you locate a reputable, English-speaking doctor, arranging payment guarantees with hospitals, and monitoring the quality of care your family member is receiving.
While medical coverage handles emergencies, a holistic approach to your trip involves understanding How Do You Plan for Family Vacation Health? to keep everyone well.
What does trip interruption or cancellation coverage mean for families?
Trip cancellation and interruption coverage for families means you are reimbursed for prepaid, non-refundable trip costs if you have to cancel or cut your vacation short due to a covered reason. Trip cancellation applies *before* you depart, covering reasons like a child’s sudden sickness. Trip interruption applies *after* you’ve departed, covering the costs to return home early and the unused portion of your trip if, for example, a family member back home has an emergency.
Rick Steves notes that some plans offer a “Cancel For Any Reason” (CFAR) option, which typically reimburses 50% to 75% of your prepaid trip cost if you cancel for a reason not listed in the base policy.
For families, a key feature is that a covered reason affecting one family member (e.g., child gets chickenpox) can trigger a payable claim for the entire family’s cancellation. This is a critical distinction from individual policies where only the sick individual would be covered.
How does baggage and personal item coverage work for a family?
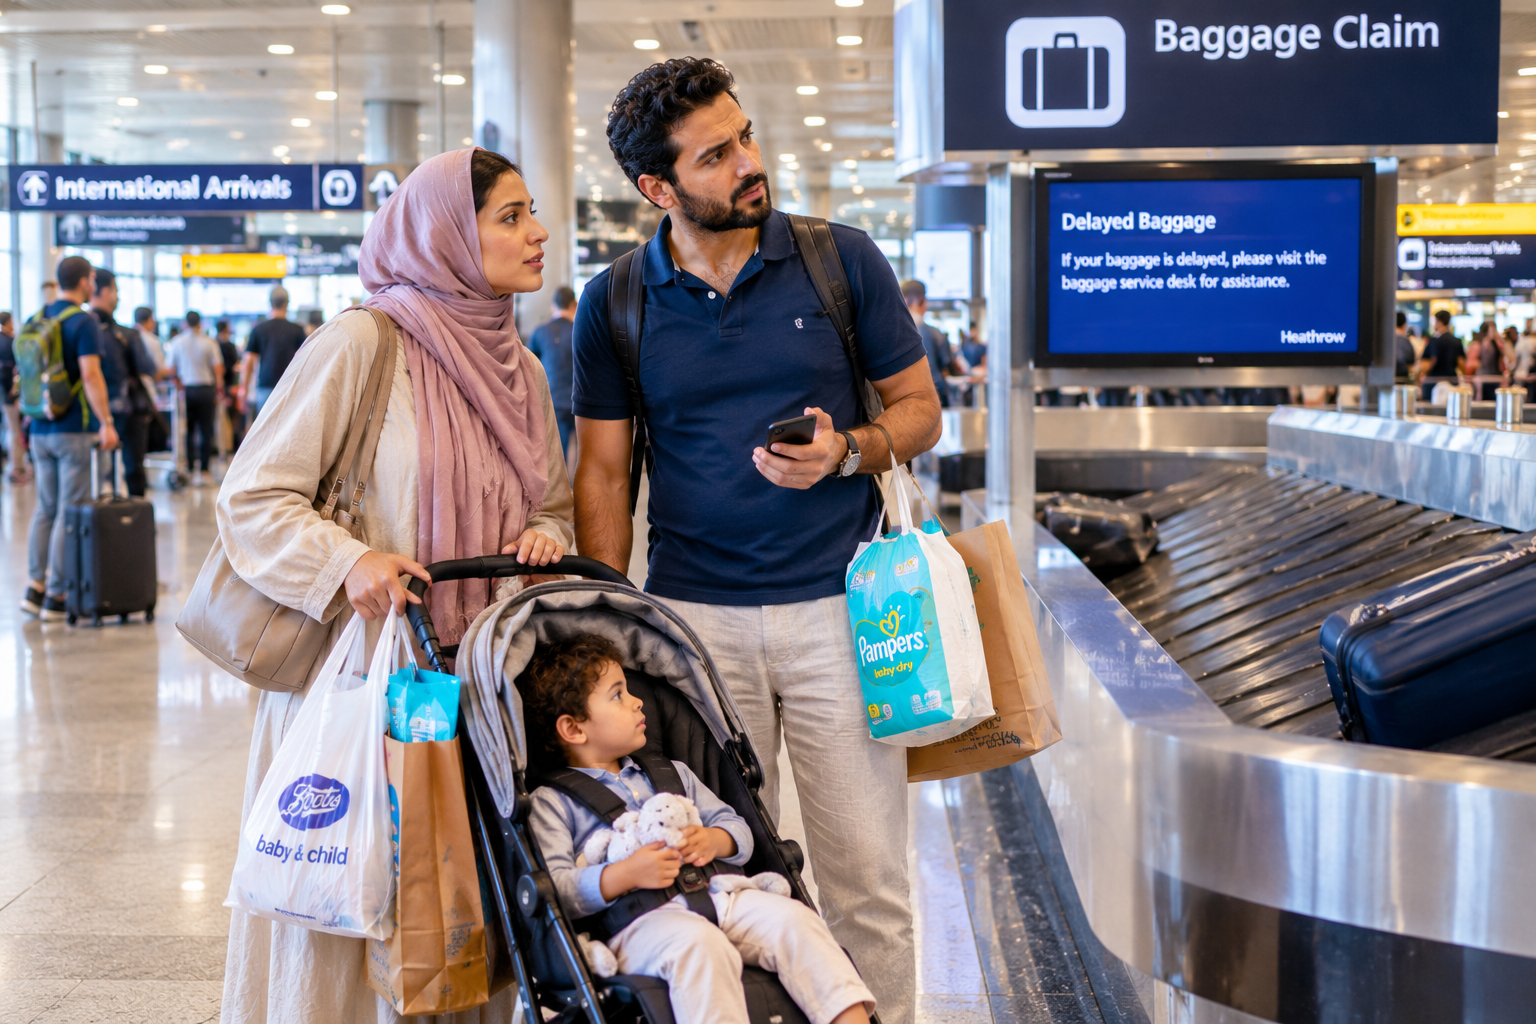
Baggage and personal item coverage for a family works by providing reimbursement for the loss, theft, or damage of your luggage and its contents, up to the policy’s specified limits. This coverage provides a per-person and a per-policy maximum benefit for lost or damaged items, and a smaller, separate benefit for expenses incurred due to baggage *delay*. For families, this means you can purchase essential items like diapers, formula, and clothing while the airline locates your delayed bags.
Allianz Travel Insurance indicates that some premium plans may offer a fixed payment of $100 for a covered baggage delay without requiring receipts for purchases.
The most valuable part of this coverage for families is often the baggage *delay* benefit, not the loss benefit. Airlines eventually find most bags; the immediate need is funds to buy crucial child-related supplies for the first 24-48 hours of a vacation, which this benefit is designed for.
3. Which types of family travel insurance coverage are essential for common vacation scenarios?
The types of family travel insurance coverage that are essential depend directly on the destination, activities, and structure of the specific vacation scenario. For a domestic beach vacation, trip cancellation and baggage coverage are key. For an international trip to a major city, comprehensive medical and evacuation coverage becomes essential, while an adventure-themed vacation requires a specific rider for high-risk activities.
| Vacation Scenario | Essential Coverage | Primary Risk Being Mitigated |
|---|---|---|
| Caribbean Cruise | Strong trip interruption and medical evacuation coverage | Unexpected medical emergencies on board, itinerary changes. |
| United States National Park Road Trip | Trip cancellation, roadside assistance add-on | Vehicle breakdown, unexpected park closures. |
| Europe City Tour | Comprehensive medical, emergency evacuation, baggage coverage | Illness abroad, lost passports/luggage. |
How do families decide on adequate medical expense coverage?
Families decide on adequate medical expense coverage by evaluating their destination’s healthcare costs, their family’s health profile, and a policy’s inclusion of medical evacuation. For international travel, especially to destinations with high healthcare costs like the United States, a minimum of $100,000 in medical expense coverage is the standard recommendation. For travel to more remote locations, ensuring the policy also has at least $250,000 in medical evacuation coverage is even more critical than the base medical amount.
According to the U.S. State Department, emergency medical evacuations to the USA can cost upwards of $200,000, depending on the location and condition.
The “adequacy” of coverage is not just the dollar amount, but whether it is *primary* coverage. A $1 million secondary policy can be less useful in an emergency than a $100,000 primary policy that pays the hospital directly and immediately.
For a more focused discussion on when this specific type of protection becomes essential, delve into When do you need emergency evacuation coverage on a vacation?
What factors should families consider for trip cancellation protection?
The primary factor families should consider for trip cancellation protection is the total sum of all prepaid, non-refundable costs for their vacation. Families must calculate the total non-refundable investment in flights, hotels, tours, and event tickets, and purchase a policy that covers 100% of that amount. Additionally, they must review the list of “covered reasons” to ensure it includes scenarios common to families, like the illness of a child or travel companion.
Travel Insured International states that one provider’s data shows that 62% of their customers opted for comprehensive travel insurance policies that include both emergency medical coverage and trip cancellation coverage.
A crucial factor is the policy’s definition of “family member.” A narrow definition might only cover illness of a child or spouse, while a better policy will extend coverage to the illness or death of a grandparent, which could also reasonably cause a family to cancel a trip.
How do families evaluate coverage for adventure activities and specific destinations?
Families evaluate coverage for adventure activities and specific destinations by carefully reading the policy’s exclusions list and, if necessary, purchasing a specific rider. The first step is to check the policy’s general exclusions for phrases like “hazardous activities,” “adventure sports,” or specific activities like “scuba diving.” If an activity is excluded, the family must purchase an optional adventure sports rider that explicitly names and covers their planned activity.
- Bungee jumping
- Rock climbing in the Alps
- Skiing out-of-bounds
- Parasailing
- Diving below a certain depth
Industry standards recommend that for high-risk activities, it is wise to look for policies that offer at least $100,000 of Emergency Medical coverage and $500,000 of evacuation coverage.
For specific destinations, the evaluation shifts to government travel advisories. Many policies contain an exclusion for “acts of war” or “civil unrest,” and traveling to a destination with a Level 3 or 4 advisory could void the entire policy, a detail families often miss.
4. How do families choose the best travel insurance plan for their vacation?
Families choose the best travel insurance plan for their vacation by using a structured decision matrix that balances cost against coverage limits, exclusions, and provider reputation. The best plan is chosen not just on price, but by confirming it provides adequate medical and evacuation limits for the destination, covers all planned activities, and has a clear and fair process for handling pre-existing conditions for all family members. Reading reviews about a provider’s claims process is a critical final step.
| Criteria | Policy A | Policy B | Policy C |
|---|---|---|---|
| Cost | |||
| Medical Limit | |||
| Evacuation Limit | |||
| Pre-existing Condition Waiver | |||
| CFAR Option |
What questions should families ask before purchasing a travel insurance policy?
Before purchasing a travel insurance policy, families should ask a series of pointed questions about coverage limits, exclusions, and the claims process to ensure the policy meets their specific needs. Key questions include: “What is the exact coverage limit for emergency medical and evacuation?”, “Is this primary or secondary medical coverage?”, “What is the look-back period for pre-existing conditions?”, and “Does this policy exclude any activities or destinations on our itinerary?”.
- What is the exact coverage limit for emergency medical and evacuation?
- Is this primary or secondary medical coverage?
- What is the look-back period for pre-existing conditions?
- Does this policy exclude any activities or destinations on our itinerary?
The most important question is often: “Can I see the full certificate of insurance before I buy?” Marketing brochures simplify coverage; the certificate is the legally binding document that contains all the actual terms, conditions, and exclusions. A refusal to provide this is a major red flag.
How do pre-existing conditions affect family travel insurance options?
Pre-existing conditions affect family travel insurance options by potentially excluding coverage for any medical issue related to that condition unless a specific waiver is obtained. A pre-existing medical condition is typically defined as any illness or injury for which you received treatment or took medication within the policy’s look-back period (e.g., the last 60-180 days). To cover this condition, families must purchase a policy that includes a “pre-existing medical condition exclusion waiver,” which is typically granted if the policy is purchased within a short window (14-21 days) of the initial trip payment.
The key is stability. Even with a waiver, a claim can be denied if the condition was not “stable” during the look-back period. This means no new medications, no changes in treatment, and no pending diagnoses. This is a critical nuance that trips up many travelers.
What are the differences between single-trip and annual multi-trip family policies?
The primary difference between single-trip and annual multi-trip family policies is the scope of coverage duration and cost-effectiveness for frequent travelers. A single-trip policy covers one specific vacation from departure to return. An annual multi-trip policy covers any trip taken within a 365-day period, typically with a per-trip duration limit (e.g., 30 or 45 days).
| Attribute | Single-Trip Policy | Annual Multi-Trip Policy |
|---|---|---|
| Cost | Higher per trip for frequent travelers | Lower per trip for frequent travelers |
| Convenience | New purchase for each trip | Single purchase for multiple trips |
| Coverage Limits | Typically higher for expensive single trips | May have per-trip duration limits |
The break-even point is typically two to three trips per year. If your family plans more than two vacations, especially if one is an expensive international trip, an annual policy is almost always more economical and convenient, as it eliminates the need to purchase a new policy for every weekend getaway or last-minute trip.
5. How do families prepare essential travel insurance documentation for their vacation?
Families prepare essential travel insurance documentation for their vacation by creating a centralized “go-kit” of digital and physical copies of all policy information and contact numbers. Preparation involves saving the policy’s Certificate of Insurance, ID cards, and the 24/7 emergency assistance phone number in multiple accessible formats. This includes printing physical copies, saving PDFs to a cloud service (like Google Drive or Dropbox), and emailing a copy to a trusted family member back home.
Pre-Trip Travel Insurance Documentation for Families
- ☐ Print two copies of the policy ID card
- ☐ Save the 24/7 Assistance number to all phones
- ☐ Download policy PDF for offline access
- ☐ Email itinerary and policy details to an emergency contact at home
What policy information should every family member have access to?
Every family member, including responsible teenagers, should have access to the insurance policy number and the 24/7 emergency assistance phone number. At a minimum, each person should carry a wallet card or have saved on their phone the policy number, the name of the insurance provider, and the international-format phone number for the emergency assistance company. This ensures that even if a family is separated during an incident, any member can initiate contact and get help.
Beyond the policy number, every adult and teen should know the primary policyholder’s full name and date of birth as it appears on the policy. When they call for assistance, this is often the first piece of information requested to pull up the family’s file.
Organizing insurance papers is just one segment of the larger task of How Do You Plan the Travel Documents for a Family Vacation?, which includes passports and consents.
How should families store and access important travel insurance contacts?
Families should store and access important travel insurance contacts using a redundant system of both digital and physical storage. The best practice is a three-tiered system: 1) Save the number in all mobile phones. 2) Keep a printed copy of the policy declaration page (which lists contacts) in each primary piece of luggage. 3) Store a digital copy in an offline-accessible folder on a phone or tablet.
The “access” part is key. Store the assistance number in your phone using the correct international dialing format (e.g., with a “+” and country code). Trying to figure out how to dial the United States from a hotel in Thailand during an emergency is an unnecessary stressor this simple preparation step eliminates.
What supporting documents are necessary for potential claims?
The supporting documents necessary for potential travel insurance claims include all receipts, reports from officials, and communications with providers. For any potential claim, you must collect itemized receipts for all expenses (medical bills, replacement items), official reports (police report for theft, airline report for lost luggage), and detailed records of who you spoke to and when. Without this documentation, even a valid claim will likely be denied.
The single most important document to get is an official report *at the time of the incident*. If your luggage is lost, do not leave the airport without a Property Irregularity Report from the airline. If something is stolen, file a police report immediately. Trying to get these documents after the fact is nearly impossible and is a primary reason claims are denied.
6. How do families manage the travel insurance claims process during or after a vacation?
Families manage the travel insurance claims process by following a strict, four-step procedure: contact, document, file, and follow-up. The process begins with immediately contacting the 24/7 assistance provider at the time of the incident, which is a requirement for many benefits. Following that, the family must meticulously collect all required documentation, formally file the claim online or via mail as soon as possible, and then proactively follow up with the claims administrator.
Step-by-Step Family Travel Insurance Claims Filing
- Contact:
- ☐ Call the 24/7 emergency assistance number immediately.
- ☐ Obtain a case number and next steps from the representative.
- Document:
- ☐ Collect itemized receipts for all expenses.
- ☐ Secure official reports (police, airline) at the time of incident.
- File:
- ☐ Complete the official claim form within the policy’s time limit (e.g., 90 days).
- ☐ Submit all documentation via online portal or mail.
- Follow-Up:
- ☐ Proactively follow up with the claims administrator.
- ☐ Keep records of all communications.
What is the immediate process for reporting an incident requiring a claim?
The immediate process for reporting an incident requiring a claim is to call the 24/7 emergency assistance number provided by your insurance policy. First, ensure the safety of all family members. Then, make the call and be prepared to provide the policyholder’s name, the policy number, and a clear, concise description of the incident.
When you call, your goal is not just to report, but to receive instructions. End the call by asking the representative, “What is the case number for this incident, and what are the exact next steps I need to take to ensure my claim is processed correctly?” This forces them to give you actionable guidance and creates a record.
How do families collect and submit evidence for a travel insurance claim?
Families collect and submit evidence for a travel insurance claim by creating a comprehensive, organized digital file for all related documentation. Collection involves gathering every related document: medical reports, police reports, receipts for all expenses, and airline communications. Submission is typically done via an online portal where you upload scanned copies or photos of these documents along with the completed claim form.
Submit a short, typed cover letter with your documentation. This letter should clearly state the policy number, the date and nature of the incident, the total amount being claimed, and a bulleted list of the enclosed documents. This “executive summary” helps the claims adjuster understand your case immediately and can speed up the process.
What are the typical timelines and expectations for family travel insurance claims?
The typical timeline for a family travel insurance claim, from submission to resolution, is between 30 and 90 days. After submission, you should expect an acknowledgement of receipt within 7-10 business days. A simple, well-documented claim for lost baggage might be paid in 30 days, while a complex medical claim requiring records from an international hospital can take 60-90 days or longer.
The timeline is almost entirely dependent on the quality of your submitted documentation. A complete, organized submission with a clear cover letter goes to the top of the pile for a quick decision. A messy, incomplete submission will be flagged for “request for further information,” which resets the clock and can add weeks or months to the process.
7. How can families avoid common mistakes when planning travel insurance for a vacation?
Families can avoid common mistakes when planning travel insurance for a vacation by focusing on three areas: reading the exclusions, understanding the timing of purchase, and insuring the full trip cost. The most common mistakes include waiting too long to buy the policy (which makes you ineligible for waivers), under-insuring the trip cost to save on the premium, and not reading the exclusions for activities and pre-existing conditions. Avoiding these pitfalls requires careful planning before purchase, not after.
A major mistake is assuming children are automatically covered for free on a parent’s policy. While many “family plans” do this, some policies require every traveler, including infants, to be explicitly named on the policy to have coverage. Always verify that every family member is listed on the final Certificate of Insurance.
What are critical travel insurance exclusions families often overlook?
Critical travel insurance exclusions that families often overlook include those related to high-risk activities, mental health conditions, and travel to destinations with government warnings. Families frequently miss exclusions for common vacation activities like skiing or scuba diving, assuming they are covered. Furthermore, most standard policies explicitly exclude claims arising from mental or nervous disorders (like anxiety-related cancellations) and will not cover any losses if traveling against a government “do not travel” advisory.
- High-risk activities (e.g., skiing, scuba diving)
- Mental health conditions/nervous disorders
- Travel against government “do not travel” advisories
- “Foreseeable events” (e.g., named hurricanes)
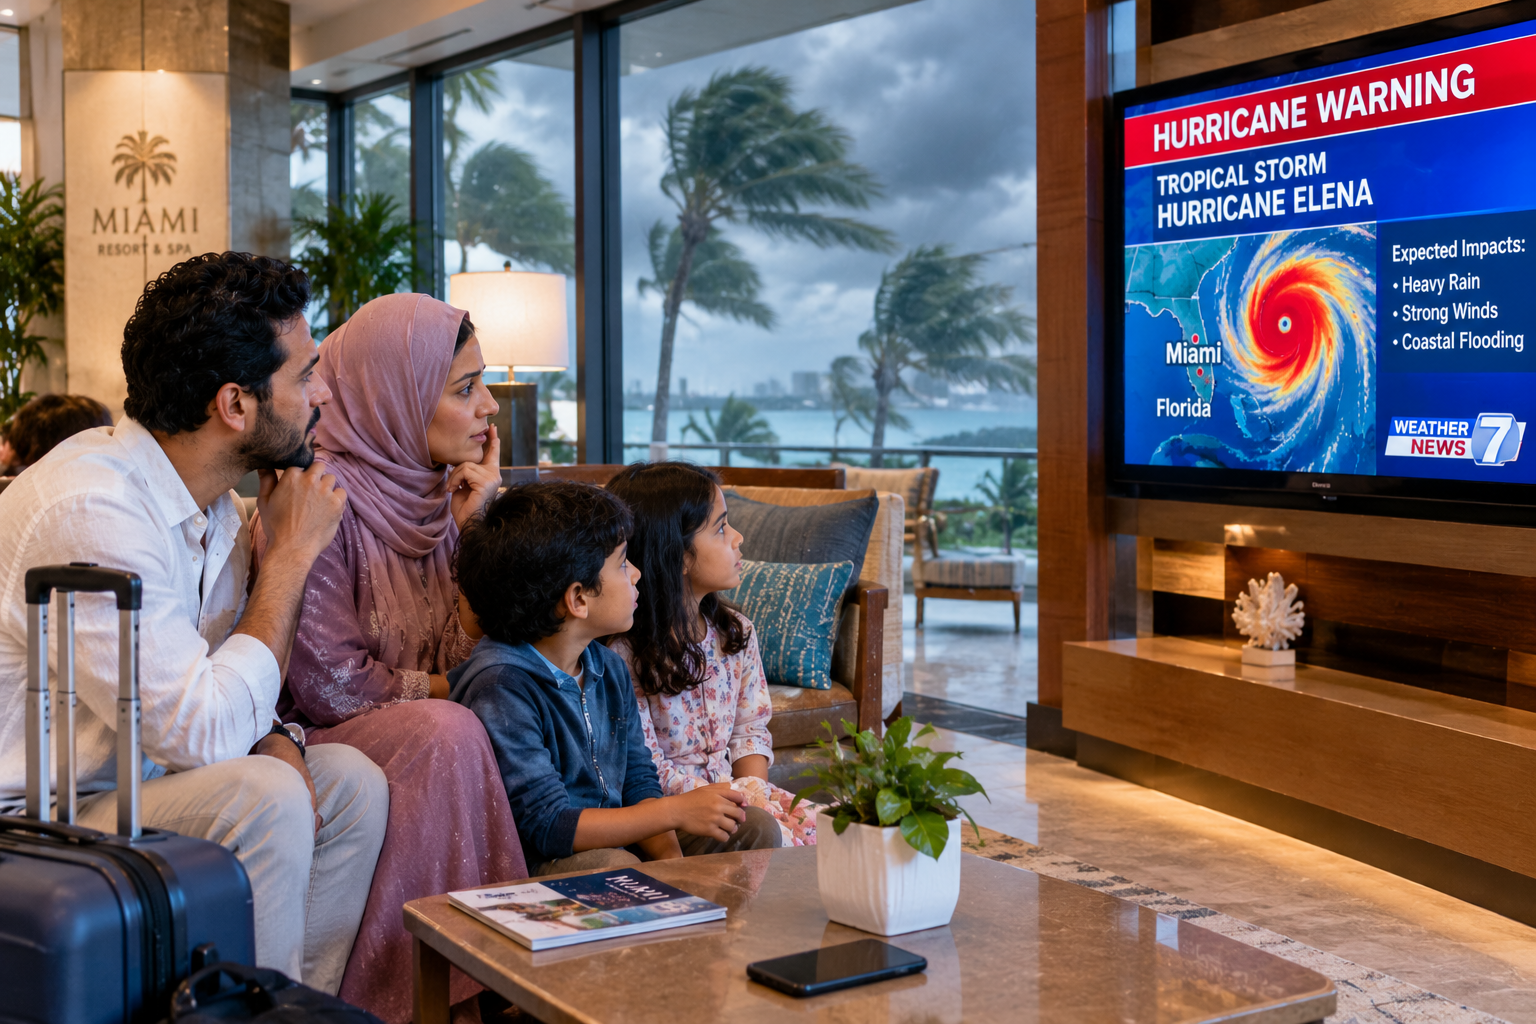
An increasingly relevant and overlooked exclusion is for “foreseeable events.” Once a hurricane is named or a major storm system is officially forecast, it becomes a foreseeable event. If you buy a policy *after* it’s named to cover a potential cancellation, your claim will be denied. Insurance must be purchased before an event is known.
How do families prevent issues with policy activation and coverage start dates?
Families prevent issues with policy activation and coverage start dates by purchasing the policy as soon as they make their first non-refundable trip payment. Your Trip Cancellation coverage becomes effective the day after you purchase the policy. However, all other coverages, such as medical and baggage loss, do not activate until your official trip departure date. Buying the policy early ensures your investment is protected from the moment you book flights or hotels.
The critical issue to prevent is a “coverage gap” for time-sensitive benefits. If you book flights on Monday but wait until Friday to buy insurance, and a family member gets sick on Wednesday, you are not covered. Buying the policy on the same day as your first payment eliminates this gap entirely.
What steps should families take if their travel plans change after purchasing insurance?
If their travel plans change after purchasing insurance, families should immediately contact their insurance provider to update their policy. The family must inform the provider of any changes to travel dates, destinations, or total trip cost. Extending a trip or traveling to a more expensive or higher-risk destination will likely require an additional premium, while failing to report these changes could void the policy entirely.
The most important change to report is an increase in the total non-refundable trip cost. If you add a non-refundable tour after buying your policy, you must call your provider and pay a small additional premium to add that cost to your total coverage amount. If you don’t, that added expense will not be covered in the event of a cancellation.
Resolution
Ultimately, planning travel insurance for a family vacation is an act of responsible financial stewardship and a critical component of ensuring a safe and successful trip. The process is a strategic one: understand the unique risks your family faces, choose a policy with comprehensive primary medical and evacuation coverage, purchase it early to access all benefits, and prepare your documentation before you depart. This diligence transforms insurance from a mere expense into a powerful tool for peace of mind.
The true value of well-planned travel insurance is not just realized in a catastrophe. It’s realized the moment a parent can choose the best care for a sick child without looking at the price, or the moment a cancelled flight becomes an inconvenience instead of a financial disaster. Plan meticulously, travel confidently.